
Small- and medium-sized enterprises (SMEs) are a big deal to the Canadian economy that powers our country’s prosperity.
The federal government defines an SME as a business establishment with one to 499 paid employees. There were 1.22 million employer businesses in Canada as of December 2020, and among them, nearly 98% (1.2 million) are considered small businesses, almost 2% (22,725) are medium-sized companies, and 0.2% (2,936) are large businesses. Moreover, over half (55%) of Canadian SMEs are considered “micro-enterprises” (businesses with fewer than four employees).
Considering how important SMEs are to the Canadian economy and their respective communities, it’s vital those organizations focus on emergency preparedness and have an SME insurance policy to protect their assets and survive the financial fallout of a fire, flood, accident, or third-party lawsuit. In addition to helping mitigate risk, business insurance can increase your organization’s credibility with customers, partners, and financial lenders.

Alarmingly, a recent Zensurance survey of Canadian small business owners and self-employed professionals finds that 40% of respondents say they don’t have a business insurance policy.
What Does an SME Business Insurance Policy Cover?
SME insurance protects a business’s assets, operations, net worth, and reputation.
In general, a comprehensive SME insurance policy will feature several coverages. Determining the coverages your business needs depends on many factors, including what kind of business yours is and the products and services you provide. For instance, a retail business may face multiple risks and require a policy that protects their merchandise, property, and equipment and safeguards them from third-party liabilities.
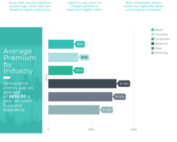
Here is a quick overview of some of the most common types of coverage that an SME insurance policy includes:
Commercial general liability (CGL) insurance: As its name suggests, CGL provides you with financial support to deal with third-party claims alleging bodily injury or property damage resulting from your daily activities. CGL typically includes product liability insurance (a must-have for any company that manufactures, distributes, or sells products or food).
Commercial property insurance: Think of commercial property insurance as you would a residential home insurance policy in that commercial property insurance protects a business property, its contents, and inventory from damage or loss resulting from a fire, flood, severe weather, theft, or vandalism. It usually includes business interruption insurance or can be added to your policy as a rider. Business interruption coverage is a potential safety net if you close your business for repairs due to an insured loss. It provides you with funds to cover your operating costs, rent, employee payroll, and more.
Cyber liability insurance: Any SME or self-employed professional with a website or a point-of-sale system needs to think about cybersecurity. That means including cyber liability protection to your overall policy to cover you if your company suffers a data breach or cyber-attack (an increasingly common threat to organizations of all sizes).
Professional liability insurance: Self-employed professionals such as consultants, accountants, or general contractors need to think about professional liability insurance. Also called errors and omissions (E&O) insurance, professional liability covers you for claims or third-party lawsuits if you make a mistake or are accused of negligence, misconduct, or failing to deliver a service as promised.
Commercial auto insurance: If you have one or more vehicles for business purposes, you should have a commercial auto insurance policy. Private-passenger car insurance is not designed to cover damages or loss claims for business vehicles.
There may be other coverages you may require to protect your business adequately. Speak to a licensed business insurance broker about customizing your policy to reflect your company’s needs.
How Can an SME Get Business Insurance?
Getting an SME insurance policy through Zensurance is quick and easy.
Fill out an online application to get a free quote. Our team of licensed brokers can provide you with support and advice on your insurance options and will shop our partner network of over 50 providers to find the policy you need at the best price available.
Sign Up for ZenMail
"*" indicates required fields
Recent Posts

What You Need to Know About Vacant Commercial Property Insurance
An empty building isn't a safe building. Vandalism, burst pipes and liability claims don't stop when your tenant moves out – and your existing policy may stop covering them. Here's how vacant commercial property insurance fills the gap.
What Is Short-Term Rental Insurance for Airbnb and VRBO Hosts in Canada?
Insurance companies treat homesharing as a commercial activity, which means your homeowner policy likely won't cover you when a guest checks in. Here's what Airbnb and VRBO hosts in Canada need to know about short-term rental insurance and the gaps it fills.
What Insurance Does a Home-Based Bakery in Canada Need?
Your homeowner's policy almost certainly won't cover your cupcakes. Here's what home-based bakery insurance includes, what it costs, and why product liability is the coverage you can't skip.