
Quick Answer: How do you winter-proof a commercial property? Clear snow and ice from all walkways daily and log every application. Keep indoor heat at a minimum of 18°C around the clock. Insulate exposed water pipes. Have your roof, gutters, and HVAC system inspected before the first freeze. Then confirm your commercial property insurance covers winter storm damage, burst pipes, and business interruption.
Canadian winters deliver harsh storms, extreme cold, and unpredictable conditions. And while the season offers its rewards – hockey, skiing, sledding – heavy snow, freezing rain, ice buildup, and high winds can damage your commercial property or injure a customer on your front walk.
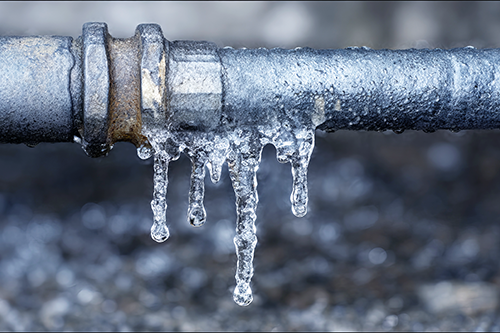
For Canadian small business owners, one bad week of weather can lead to costly repairs, liability claims, and weeks of lost revenue.
On a brighter note, most winter property damage is preventable. Snow and ice management, HVAC maintenance, and a pre-season roof inspection cover the majority of your exposure. The rest, such as internal damage from a burst water pipe, a roof that gives way, or a ferocious storm that forces you to close for a month, is what commercial property insurance is for.
What Is Commercial Property Insurance and What Does It Cover?
Commercial property insurance covers physical loss or damage to your business property and its contents from severe weather, fire, water damage, theft, or vandalism. It’s also called business property insurance or commercial building insurance.
A policy typically covers:
- Building damage: Repairs or replacement for a property you own after a fire, storm, or other unforeseen event
- Tenant improvements you’ve made to a leased space that can’t be removed, like carpeting, lighting, or paint
- Inventory and merchandise, including food stock, lost to fire, theft, vandalism, or water damage
- Equipment, fixtures, and furnishings that need repair or replacement
- Electronics and office equipment, whether damaged or stolen inside or outside your office
What Doesn’t Commercial Property Insurance Cover?
Commercial property insurance doesn’t typically cover:
- Mysterious disappearance of items, where the cause of loss can’t be explained
- Property left at vacant or unoccupied locations for more than 30 days (that requires vacant property insurance)
- Wear and tear to equipment from regular use
- Internal theft of cash or securities, or forgery and fraud (that’s commercial crime insurance)
Flood and sewer backup protection are often add-ons rather than standard inclusions, too. Worth confirming before the spring melt.
How Much Does Commercial Property Insurance Cost in Canada?
Commercial property insurance varies between insurers. What your premium will cost depends on your building, your contents, and your claims history.
Your premium depends on:
- The type of property and its location
- The age and condition of the building
- What your business does, who it serves, and the value of your contents and inventory
- The coverage limit and deductible you choose
- Your claims history
The best way to know what a policy may cost you is to get a free commercial property insurance quote.
10 Ways to Winter-Proof Your Commercial Property
Here are 10 commercial property winter protection tips for business owners to consider to protect their businesses and finances over the long, dark winter months:
1. Clear Snow and Ice, and Keep a Log
Slip and fall accidents are the most common winter liability claim businesses face. The log is the part most owners skip, and it’s the part that wins claims.
Clear your property after every storm. If you’re managing a larger site, hire a snow removal contractor, and ask for proof of their liability insurance before they start. Mark curbs, speed bumps, and ramps with high-contrast paint or stakes.
Stock up on sand or de-icing salt for driveways, sidewalks, and pathways leading to your entrances and exits. Keep emergency exits and delivery bays clear.
Then write it down: date, time, what you cleared, what you applied. If a customer files a claim in March over a February fall, that logbook is your defence.
2. Roll Out Anti-Slip Mats at Every Entrance
Snow tracked indoors turns into slick floors fast. That’s your second slip-and-fall exposure, and it happens inside, where you’re clearly responsible.
Place anti-slip mats inside every entrance. Keep a mop and bucket within reach of the door and make sure staff know to use them before water pools.
3. Post Warning Signs Where Floors Get Wet
Indoors or out, give customers fair warning. Prominent, visible signage in wet areas is cheap, and it’s evidence you took reasonable care if a claim ever lands.
4. Check Handrails on Stairs and Ramps
If your property has stairs or ramps, grab every handrail and pull. Loose hardware on an icy staircase is a claim waiting to happen.
5. Clear Gutters and Downspouts to Prevent Ice Dams
Eavestroughs and downspouts clog with fall leaves and debris. When meltwater can’t drain, it backs up under your shingles and into your ceiling.
Clear the debris or hire a contractor to do it, and book a mid-winter inspection. Flat roofs need this most. The goal is simple: get freezing rain and melting snow off your roof and away from your foundation.
6. Inspect Your Fire Safety Equipment
Fire is a year-round threat, but winter stacks the deck: space heaters, dry indoor air, and holiday decorations all show up at once. Review your fire safety measures at least twice a year.
Check that extinguishers work and are visible and accessible. Test every smoke, fire, and carbon monoxide alarm and replace the batteries. Walk your team through your emergency procedures again.
Decorating for the holidays? Keep decorations away from indoor heat sources, and only hang lights rated for outdoor use outside.
7. Hold a Steady Indoor Temperature
Keep the heat on and set a minimum off-hours temperature of 18°C to prevent mould and frozen pipes that can crack and leak.
Replace furnace filters, test your thermostats, and install smart temperature sensors. They’re inexpensive, and they’ll text you at 3 a.m. if the heat fails while you’re asleep.
Book an HVAC inspection before the cold sets in, not after. Contractors are booked solid the week of the first deep freeze.
8. Have Your Roof Inspected Before the Snow Loads Up
Hire a roofing contractor now to check for loose shingles, leaks, and weak spots that could turn into ice dams, or a collapse under a heavy snow load.
9. Insulate Your Pipes and Find Your Shut-Off Valve
Frozen and burst pipes are one of the costliest winter claims a commercial property owner can face. A single break can flood a floor overnight.
Hire a plumber to inspect your plumbing and flag problems like leaking faucets. Insulate pipes that can freeze even with the heat on (the ones under sinks and in cabinets where warm air doesn’t circulate).
And know where your main water shut-off valve is. Better yet, tag it and show every manager on staff. A burst pipe found in five minutes is a repair. Found in five hours, it’s a rebuild.
10. Light Up the Exterior and Watch It
Theft and vandalism might not seem like a winter risk, but crime doesn’t take a holiday, and long, dark nights make an empty building tempting.
Keep your exterior lit around the clock. Install monitored surveillance cameras and an alarm system, and post signage warning that the property is under video surveillance.
One more: clear valuable products out of window displays at the end of each day to prevent “smash-and-grab” robberies.
What Insurance Covers Winter Damage to a Commercial Property?
Three coverages carry most of your winter risk:
- Commercial general liability insurance, also called slip-and-fall insurance, covers third-party bodily injury, like a customer’s slip-and-fall, or third-party property damage claims on your premises or at a client’s site.
- Commercial property insurance covers damage and loss to your building, contents, and inventory from storms, fire, water damage, theft, and vandalism.
- Business interruption insurance covers lost income if an insurable event forces you to close for repairs. It’s sometimes bundled into a commercial property policy, but not always. Ask for it to be included.
A slip-and-fall claim, a caved-in roof, or a month of closure for water damage can each run into the tens of thousands. That’s the arithmetic.
Frequently Asked Questions About Commercial Property Insurance in Canada
How do I keep pipes from freezing in a commercial building?
Keep indoor temperatures at a minimum of 18°C, including overnight and on weekends. Insulate pipes in unheated areas and inside cabinets where warm air doesn’t reach. Install a smart temperature sensor that alerts your phone if the heat drops, and know where your main shut-off valve is.
Does commercial property insurance cover burst pipes?
Yes, commercial property insurance generally covers sudden and accidental water damage from a burst pipe. It won’t cover damage from gradual leaks, poor maintenance, or a pipe that froze because the heat was left off in an unoccupied building.
Is a business owner liable if a customer slips on ice outside?
A business can be held liable if it failed to take reasonable steps to clear snow and ice. Documented snow removal and de-icing, with dates and times, plus visible warning signage are your strongest defence. General liability insurance covers these claims.
Does commercial property insurance cover roof collapse from snow?
Most commercial property policies cover roof collapse caused by the weight of snow or ice. Coverage can be denied if the collapse resulted from deferred maintenance or a pre-existing defect, which is why a pre-winter roof inspection matters.
How much does commercial property insurance cost in Canada?
Premiums may range between insurers for an annual policy, depending on the building’s age, location, and construction, the value of your contents, your coverage limits and deductible, and your company’s claims history. The best way to know what a policy would cost your business is to get a free quote.
Get Covered Before the Flurries Swirl
If you want better coverage at a lower cost, we can help.
Complete our online application for a free quote in minutes.
With our expertise in commercial insurance and a partner network of more than 50 insurers, our licensed brokers will find you a low-cost policy built around your specific risks.
– Updated October 5, 2026.
Related Posts

Categories
Related Posts
How Much Is Commercial Vehicle Insurance in Canada?
The cost of commercial vehicle insurance in Canada varies by insurer. Here's what drives your rate, why business vehicles cost more to insure than personal ones, and how to keep your premium down.
Winter-Proofing Your Commercial Property: 10 Steps to Take Before the First Freeze
Don't let winter put your business property at risk. A few hours of prep in the fall can save you a five-figure repair bill in January. Here are 10 ways Canadian small business owners can safeguard their commercial property this season, and how commercial property insurance covers what prevention can't.
12 Tips for Buying the Right Business Insurance in Canada
61% of Canadian small business owners surveyed have no coverage at all. That's a gamble few can afford to take if something goes wrong. Here's how to buy the right business insurance, and avoid paying for what you don't need.