
RMT insurance in Canada typically costs around $123 per year for an independent RMT with $2 million in malpractice coverage. Clinic owners with staff, property, and equipment pay more. Here’s what drives your premium, and what your provincial college requires you to carry.
Most independent Registered Massage Therapists (RMTs) in Canada pay around $223 per year for a policy combining $2 million in malpractice coverage with commercial general liability. That’s the baseline, what you actually pay depends on how you practise. An RMT renting a treatment room carries a different risk profile than a clinic owner with four therapists on staff and a waiting room full of equipment.
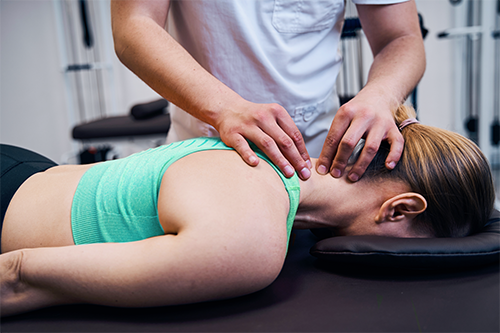
Those are starting points, not quotes. Your actual premium reflects your revenue, location, and the modalities you offer. To find out your exact rate, get a free quote in about 3 minutes.
What Factors Affect Your Massage Therapist Insurance Premium?
Insurers price your policy on risk. Six factors move the needle most:
- Annual revenue. More clients means more exposure. A part-time RMT billing $30,000 a year pays less than a full-time practice billing $90,000.
- Your location. A fixed clinic, a home studio, or clients’ homes each carry different risks. Mobile RMTs typically need equipment coverage added; home-based clinics need contents coverage your home insurance won’t provide.
- Services you offer. Hot stone, cupping, prenatal, and deep tissue carry different risk ratings than relaxation massage. Tell your broker everything you offer. An undisclosed service may void a claim.
- Coverage limits. $2 million per occurrence is the floor in regulated provinces like Ontario. Bumping to $5 million costs less than most therapists expect.
- Claims history. A clean record keeps your premium down. Prior claims don’t make you uninsurable, but they raise the price.
- Staff and contractors. Hiring other RMTs or renting chairs to independent practitioners changes your liability picture entirely.
Is Liability Insurance a Legal Requirement for Massage Therapists in Canada?
In the five provinces where massage therapy is a regulated health profession, yes, your college requires professional liability insurance as a condition of registration.
Elsewhere, it’s not law, but clinics, landlords, and contracts almost always require proof of coverage anyway.
| Province | Regulator |
| Ontario | College of Massage Therapists of Ontario (CMTO) |
| British Columbia | College of Complementary Health Professionals of BC (CCHPBC) |
| New Brunswick | College of Massage Therapists of New Brunswick (CMTNB) |
| Newfoundland and Labrador | College of Massage Therapists of Newfoundland and Labrador (CMTNL) |
| Prince Edward Island | College of Massage Therapists of PEI (CMPEI) |
| Saskatchewan | Saskatchewan College of Massage Therapy (in development) |
| All Other Provinces | Not regulated |
Two things worth knowing even if you’re outside a regulated province. First, regulation is spreading – Saskatchewan’s college is being established, and Alberta, Manitoba, and Nova Scotia are actively pursuing it.
Second, extended health plans only reimburse treatments from registered therapists in regulated provinces, so your clients’ benefits, and your bookings, depend on your standing.
What Does Massage Therapist Insurance Cover?
Most RMT insurance policies combine four coverages. Each one answers a different “what if”:
Malpractice (Professional Liability) Insurance
The core of your policy, and what your college requires. It’s designed to cover claims of professional negligence, errors, omissions, and allegations of substandard treatment, whether or not the claim has merit. Legal defence costs alone can run into tens of thousands of dollars, and malpractice coverage may help to pay them.
Commercial General Liability (CGL) Insurance
May cover third-party injuries and property damage that aren’t about your treatment. CGL is designed to cover incidents such as a client slipping on a wet floor, tripping over a table leg, or having an allergic reaction to the oils or lotions you use.
Commercial Property Insurance
Designed to protect your table, tools, linens, and clinic contents against fire, theft, water damage, and vandalism (including equipment stolen from your vehicle if you’re mobile). Adding business interruption coverage means lost income may be covered too if a fire or flood closes your space for repairs.
Cyber Liability Insurance
You hold client health records, booking data, and payment information; that’s exactly what cybercriminals target, and small practices are soft targets. Cyber coverage may pay for legal advice, client notification, credit monitoring, and system recovery after a breach.
How Can Massage Therapists Pay Less for Insurance?
You don’t need to be underinsured to save money. Here are four moves that may help lower your premium without leaving gaps:
- Bundle your coverages. One policy combining malpractice, CGL, property, and cyber costs less than buying them separately, and eliminates the gaps between standalone policies.
- Right-size your limits. Carry what your college and contracts require. Paying for $10 million in aggregate coverage when $5 million satisfies every requirement you have is money down the drain.
- Pay annually. Most insurers charge a premium for monthly instalments. Paying the year upfront may help you save.
- Compare before you renew. Auto-renewing the same policy year after year is how premiums creep. A brokerage that shops multiple insurers does the comparing for you.
Frequently Asked Questions About Massage Therapist Insurance
Doesn’t my association membership already cover me?
Partially. Association group plans typically provide malpractice coverage, but they often exclude or limit commercial general liability, and they rarely cover your property, equipment, or cyber exposure. If you rent a treatment room, run a home clinic, or store client records digitally, you likely have gaps.
Do mobile massage therapists need different insurance?
Yes. Mobile RMTs need coverage that follows them, like equipment protection for tools in transit and liability that applies in clients’ homes, and not just a fixed clinic address. Confirm your policy covers multiple work locations.
Am I covered if I rent a room in someone else’s clinic?
The clinic’s insurance covers the clinic; not you. You still need your own malpractice and liability coverage, and many clinic owners require proof of it (a certificate of insurance) before you can start.
Does my insurance cover cupping, hot stone, and other treatments?
Only if your broker or insurer knows about them. Disclose every treatment you practise when you apply. Any treatments your policy doesn’t include may not be covered when a claim arises.
Get the Right Massage Therapist Insurance at the Right Price
The fastest way to find out what you’d actually pay for a RMT insurance policy is to get a free quote. It takes about 3 minutes, costs nothing, and there’s no obligation.
Fill out our online application and let our licensed brokers shop our partner network of over 50 insurers to find the coverage your practice and your college require.
Our brokers will customize it to suit your practice and budget, and issue your policy documents and a certificate of insurance, often the same day.
Related Posts

Categories
Recent Posts
How to Protect Your Retail Business on Black Friday and Cyber Monday
Canadians are spending less this holiday season and packing it into four days. For retailers and online sellers, that means thinner margins with more riding on Black Friday and Cyber Monday. Here's what can go wrong across the holiday shopping season, and the insurance coverage that protects what you earn.
Does Your Canadian SaaS Company Need Tech Errors and Omissions Insurance?
Tech E&O insurance protects Canadian SaaS companies when a bug or bad data costs a client money. What it covers, what it costs and how to get a free quote.
9 Reasons Why Massage Therapists Need Insurance
Your premium depends on how you practise. Here’s what Canadian RMTs typically pay for coverage, what your provincial college requires, and how to pay less without leaving gaps.