
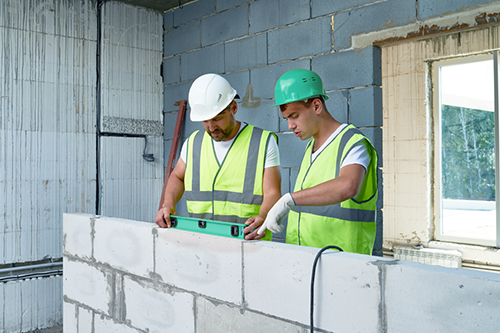
All contractors need general liability insurance as part of their overall policies. No doubt you already knew that.
General liability insurance covers you for third-party bodily injuries and third-party property damages resulting from your work and during your usual business activities. It also typically includes product liability insurance to cover bodily harm or property damage to a third party caused by any product you manufacture, distribute, supply, or sell.
Furthermore, general liability insurance also usually includes coverage for your completed operations.
Therefore, after a job is done and if a situation arises unexpectedly – for example, a former customer calls you in a rage to tell you the kitchen cabinet you installed for them several months ago suddenly broke free from the wall, smashing the dishware inside it, and leaving large holes in the drywall, and damaging their floor – the completed operations portion of your general liability coverage is designed to pay for the necessary repairs.
Related Posts
Sign Up for ZenMail
"*" indicates required fields
Categories
Is There a Difference Between Completed Operations and Installation Floater Insurance?
Indeed, there is. Completed operations coverage within general liability insurance covers the jobs you do for a customer if they suffer an injury or property damage after the work is done.
On the other hand, installation floater insurance is an optional coverage you can add to your policy to pay for damages or losses to the materials you’re using to complete a project before or during installation.
For instance, if building materials you acquire for a renovation are damaged by fire, water, extreme weather, vandalism or are stolen while in transit, stored at a temporary site or the job site before installation, an installation floater is designed to pay to replace those materials.
As with any insurance, coverage or policy limits are the maximum amount your insurer will pay for a single insurable damage or loss claim.
Contractors Are Not Immune to Lawsuits or Damage Claims
Here’s something else to bear in mind: If you think the likelihood of an unsatisfied or angry customer taking legal action against you is low or non-existent, reconsider that perspective.
A recent national Zensurance survey of Canadian consumers found a majority would launch a lawsuit against an independent professional or small business owner for a variety of reasons. For example, a consumer would sue a contractor if they made a mistake that damages their property and causes them financial harm.
How Contractors Can Get Low-Cost Insurance Coverage Quickly
Protecting your finances and career with a low-cost, customizable contractor insurance policy is easy through Zensurance.
Let’s get to work building the comprehensive protection you need. For a free quote, start by filling out our online application.
Our knowledgeable team of brokers will shop our network of over 50 Canadian insurance providers to find the policy that best suits your needs and budget, ensure you have adequate coverage limits, answer your questions, and tailor the policy to meet your requirements.
Recent Posts
Sole Proprietor Insurance in Canada: What You Need and What It Costs
When you’re unincorporated, a lawsuit lands on you, not your business. Here’s the coverage that changes that, and what it costs.
Liquor Liability Insurance vs Host Liquor Liability Insurance: What’s the Difference?
One covers businesses that sell alcohol, the other covers everyone who simply serves it, and the gap between them is where uninsured claims live.
Holiday Markets and Craft Fairs: Why Organizers Ask Vendors for Proof of Insurance
Booking a booth this holiday season? Here’s why Canadian market and festival organizers require vendors to show proof of insurance, and how to get covered before the event starts.