
With 10 days to go until the first day of spring arrives (it’s true!), now’s the time for landscapers and lawn care professionals to gear up for the busy season ahead.
Preparing now to serve and attract new customers will give your business the edge. That means taking action in various ways, including inspecting mowers, trimmers, blowers and other tools, stocking up on fertilizers and landscaping materials, and contacting your customers to book appointments.
It also means ensuring your business has the customized landscaping insurance it needs.
Related Posts

Sign Up for ZenMail
"*" indicates required fields
Categories
How Does Insurance Protect Landscaping Businesses?
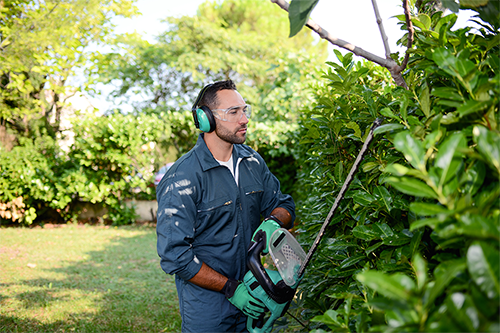
Business insurance is vital protection for landscaping and lawn care professionals. The nature of the work landscaping professionals do can involve many liability risks that could cost a landscaper thousands of dollars to overcome.
For example, a landscaper’s tools and equipment could be vandalized or stolen, a fire could ignite at your place of business, or if you make a mistake at a customer’s property that causes damages or injures someone, you may be liable to pay the costs.
Business insurance covers unexpected scenarios and accidents that can lead to expensive damages, lawsuits, or lost income.
What Does a Landscaping Insurance Policy Include?
A landscaping insurance policy typically includes the following coverages:
- General liability insurance to cover third-party bodily injury and property damage claims.
- Tools and equipment insurance covers the portable tools and equipment landscapers use if vandalized, stolen, or damaged by fire or water.
- Pollution liability insurance covers claims of environmental damage and third-party bodily injury or property damage claims caused by fertilizers, pesticides, and other chemicals.
- Commercial auto insurance covers business vehicles and trailers landscapers use to haul their crews and equipment.
- Commercial property insurance protects your landscaping business’s office or business property if damaged by fire, natural disasters and extreme weather, vandalism, theft, and internal water damage.
Your business may need to include other types of insurance in a policy. If you have questions about what your policy should contain, speak to a licensed Zensurance broker.
Where to Get Low-Cost Landscaping Insurance Fast
Zensurance is Canada’s leading small business insurance provider, trusted by hundreds of thousands of small business owners and independent professionals for their insurance needs.
Fill out our online application now for a free landscaping insurance quote.
Let our team of knowledgeable brokers shop our partner network of over 50 insurers to get the coverage your landscaping business needs, customize it to suit your operations, and issue a certificate of insurance so you’re ready for the season ahead.
Recent Posts
What Insurance Does a Cybersecurity Consultant Need?
Cybersecurity consultants in Canada typically need four coverages: professional liability (errors and omissions), cyber liability, commercial general liability, and business contents insurance. The reason is simple. Clients blame the person who told them they were secure.
6 Real Cyber Insurance Claims Canadian Small Businesses Filed in 2026
Phishing, ransomware, and DDoS attacks keep evolving, and Canadian small businesses are squarely in cybercriminals' crosshairs. Here are six real claims we helped clients recover from – payouts from $25,000 to more than $250,000 – and what they mean for your business, whatever industry you're in.
What Type of Insurance Do Software Developers Need?
Software developers build the systems everything else runs on, and carry the liability when something breaks. Here's the coverage Canadian devs, freelancers, and dev shops actually need, and what each policy does when a claim lands.