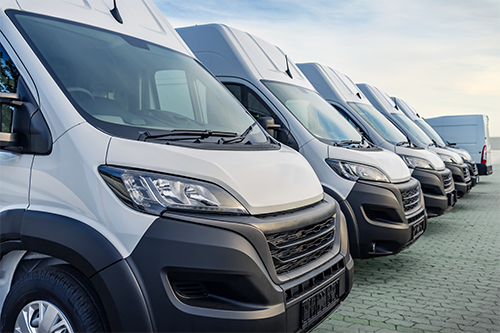
If your business operates four or more vehicles (and sometimes as few as three), you likely need commercial fleet insurance. It covers every vehicle your company owns under a single policy with one renewal date, one set of documents, and pricing based on your fleet’s overall risk rather than each vehicle in isolation. For most businesses, that works out cheaper than buying individual commercial auto policies.
Some small businesses have several commercial vehicles they need insured, and buying a separate commercial auto policy for each one gets expensive fast.
That’s why commercial fleet insurance (also called fleet vehicle insurance, fleet car insurance, and vehicle fleet insurance) makes economic sense. It protects multiple vehicles a company owns, whether those wheels are used to deliver finished goods, transport raw materials and equipment, or shuttle people from one location to another.
This guide explains what commercial fleet insurance is, what it covers and doesn’t cover, its cost, and tips for lowering your annual premium.
What Is Commercial Fleet Insurance?
Commercial fleet insurance is commercial auto insurance designed to cover multiple vehicles operated by a business under a single policy. It helps simplify administration by covering eligible vehicles with one policy instead of managing separate policies for each vehicle.
Instead of rating each vehicle on its own, insurers assess your fleet’s combined risk (your claims history, your drivers, how far the vehicles travel, and what they haul). That’s why a clean claims record across your whole fleet can pay off at renewal.
Which Businesses Need Commercial Fleet Insurance?
Any business that owns and operates a group of vehicles for commercial purposes. Common examples include:
- Courier and last-mile delivery companies
- Food trucks, caterers, restaurants using vehicles to pick up supplies
- Contractors and skilled trades with crews travelling between job sites
- Landscaping and snow removal operators
- Moving companies
- HVAC, plumbing, and electrical service businesses
- Food and beverage distributors
- Medical transport and shuttle services
If your vehicles are registered to your business and used to earn revenue, a personal auto policy won’t protect them.
What Does Commercial Fleet Insurance Cover?
A commercial fleet policy covers the same protections as a standard commercial auto policy – third-party liability, accident benefits, uninsured auto, and direct compensation-property damage – applied across every vehicle on the policy. Although mandatory coverages vary between provinces, a typical policy includes:
- Third-party liability. If you get into an accident for which you are deemed responsible or at fault, third-party liability coverage will cover the cost of damages and injuries to another driver or person or their property.
- Accident benefits. Accident benefits cover your expenses if you are injured or killed in a car accident. These benefits may include income replacement, coverage for medical rehabilitation, and funeral and death expenses.
- Uninsured auto. If you are involved in a collision with an uninsured motorist deemed to be at fault for the crash, an unidentified motorist, or a driver who commits a hit-and-run, uninsured automobile insurance is designed to compensate you for damages to your vehicle, medical expenses, or compensate your family if you are killed.
- Direct compensation-property damage (DCPD). In provinces with no-fault insurance systems, DCPD allows you to deal with your insurance provider directly for compensation if you are hurt or your vehicle is damaged in an accident that you did not cause.
There are optional coverages you can add. The most common are:
- Collision or upset insurance. If you get into an accident with another vehicle or smash into a stationary object such as a traffic light, collision insurance will cover the cost to repair or replace the vehicle up to its coverage limit minus a deductible.
- Comprehensive insurance. Comprehensive covers repairs or replacement if your vehicle is vandalized, stolen, or damaged by fire, explosion, severe weather, flying objects, or a collision with an animal. You pay the deductible; your insurer covers the rest.
- All perils insurance. A combination of collision and comprehensive coverages, all perils also covers theft of a vehicle by one of your own employees.
What Doesn‘t Commercial Fleet Insurance Cover?
A commercial fleet policy won’t cover personal use of a business vehicle, privately owned vehicles your employees drive for work, or a household’s personal cars. For example, a family cannot purchase it to cover the cars driven by primary and secondary drivers who live together. However, you can add personal use vehicles on a fleet policy provided the vehicles are registered to the same business.
If your employees regularly use their own vehicles for company errands, ask a broker about non-owned commercial automobile coverage. It’s a separate add-on, and it’s one of the most commonly overlooked gaps in a fleet program.
Note: A fleet policy covers the vehicle, not what’s inside it. If you haul goods or client property, ask a broker about cargo insurance.
How Many Vehicles Can Be Covered By Commercial Fleet Insurance?
A minimum of four vehicles are covered by one commercial fleet policy.
For example, in Ontario a fleet generally refers to a group of at least four or cars, pickup trucks, vans, or SUVs that meet specified ownership and business-use requirements.
There’s usually no upper limit. Larger fleets often get more competitive pricing, since insurers have more data to rate against.
What Is the Difference Between Commercial Auto and Commercial Fleet Insurance?
The coverages are essentially the same. The difference is scope and how the policy is priced. Commercial auto insurance covers a single vehicle. Fleet insurance covers a group of vehicles under one policy, rated on the fleet’s combined risk.
| Commercial Auto Insurance | Commercial Fleet Insurance | |
| Vehicles covered | One | Typically four or more |
| Policies to manage | One per vehicle | One total |
| Renewal dates | One per vehicle | Single renewal |
| How it‘s rated | Per vehicle and driver | Across the fleet’s combined claims history |
| Adding a vehicle | New policy | Added to the existing policy |
Two benefits stand out for small businesses with four or more vehicles:
- Less administration. One policy, one renewal date, one set of documents. Adding or removing a vehicle mid-term is a phone call, not a new application.
- Lower cost. One fleet policy covering five SUVs is typically cheaper than five commercial auto policies. The larger the fleet, the more room insurers have to compete for your business, and the more your claims record works in your favour.
Does Private-Passenger Auto Insurance Cover Business Vehicles?
No. A personal auto policy is not designed to protect a vehicle used for commercial purposes, and a claim involving business use can be denied.
There may be exceptions depending on your policy and the insurance provider underwriting it. For example, if yours is a home-based business and you use your car to drive to a client’s location for a meeting, you may be able to add occasional business use to that policy. But don’t assume that’s the case.
Most small business owners need a commercial auto or fleet policy for any vehicle they regularly use for work. Commercial policies do cost more than personal ones because business vehicles carry higher liability and property damage limits, spend more time on the road, and face a greater risk of collision, vandalism, and theft.
How Much Does Commercial Fleet Insurance Cost in Canada?
There’s no flat rate for fleet insurance. Premiums are quoted per fleet, based on your vehicles, your drivers, and your claims history, which is why two businesses with five trucks each can pay very different amounts. Most Zensurance fleet vehicle clients pay between $7,000 and $20,000 depending on the size of their fleet and vehicle loss history.
Insurance providers consider several factors when pricing your policy, including:
- The number of vehicles in your fleet and the type of vehicles
- The industry your business is in and the location of your company
- The annual kilometres each vehicle travels and where it’s regularly parked or stored
- What the vehicles are used for (transporting goods, people, or both)
- Your business’s collision and claims history
- The number of drivers you have, their ages, years of experience, and respective driving records
- What your policy’s coverages are, their limits, and the deductibles
When choosing the fleet policy that suits your business, you can decide whether to pay your annual premium upfront or in monthly or quarterly installments.
Want to know what your fleet would cost to insure? Get a free quote in minutes with no obligation.
How to Lower the Cost of Commercial Fleet Insurance
One of the biggest gripes business owners have when buying commercial auto insurance is how expensive it can be, even if you’ve had no accidents or filed any claims.
Today’s vehicles are more expensive to build and repair. In many cases, the more electronics and computer-driven systems a vehicle has, the higher the cost to repair or replace it. That’s one major reason the cost of commercial auto insurance policies tends to increase year-over-year.
Here are a few ways to lower your annual premium:
- Shop Around. It’s not uncommon for business owners to automatically renew with the same provider, but it might not always be your best option. Taking a few minutes to get a free quote through Zensurance is a quick and easy way to determine if you’re getting the maximum protection you need at the best price.
- Increase Your Deductibles. A deductible is the amount of money you must pay first when filing a claim for damage or loss before your insurance provider pays. It’s typically around $1,000 on a commercial auto policy, but you can increase it. The higher the deductible, the lower your annual premium.
- Screen Your Drivers. Only allow employees with clean driving records to operate your company’s vehicles. Driver records are one of the heaviest factors in fleet pricing. One at-fault claim can affect the whole policy at renewal.
- Enrol Drivers In a Defensive Driving Course. Anyone can benefit from a defensive driving course, whether it’s the first time or a refresher. Get your drivers trained by professionals recognized by your provincial transportation ministry.
- Install Winter Tires. Have winter tires installed on your vehicles just before the cold weather arrives. Winter tires are designed to grip the road more effectively in snowy, wet, and icy road conditions and can help prevent accidents.
- Invest in Fleet Dash Cameras. Dash cameras do two jobs: they exonerate your drivers in a collision they didn’t cause, and they surface risky driving habits before those habits become claims. Some insurers offer a discount for fleet-wide installation.
- Store Your Vehicles in Secured Lots. After the working day, ensure your company’s vehicles are parked, locked, and stored in a garage or parking lot on your premises that is secured by fencing and features a 24/7 monitored video surveillance system.
Frequently Asked Questions About Commercial Fleet Insurance in Canada
What types of vehicles can be insured under a commercial fleet policy?
Cars, vans, pickup trucks, delivery vehicles, service vehicles, and heavier commercial trucks can all be covered. The vehicle’s type, weight, use, and operating territory can affect eligibility, coverage, and premiums.
What‘s the difference between ‘named driver‘ and ‘any driver‘ fleet insurance?
A named driver policy assigns specific employees to specific vehicles. An any driver policy lets any listed employee operate any vehicle on the policy. Any driver policies offer the most flexibility, but they typically cost more.
Is commercial fleet insurance mandatory in Canada?
Auto insurance is mandatory in every province for any vehicle used on public roads, and commercial coverage is required when vehicles are used for business. Whether a business must use a specific fleet program depends on provincial rules and an insurer’s requirements. Don’t assume a personal auto policy covers a business vehicle. It usually doesn’t.
Is commercial fleet insurance cheaper than insuring business vehicles separately?
Usually, yes. Fleet insurance policies may offer efficiencies and more competitive pricing because an insurer evaluates the business’s overall fleet risk. The final premium depends heavily on claims experience, vehicle types, drivers, usage, and other risk factors.
Does fleet insurance cover personal use of a company vehicle?
Not automatically. Personal use, commuting, and other non-business uses should be clearly disclosed to a broker. As long as it is disclosed to a broker, personal use of a business vehicle can be added to a fleet policy. Get written confirmation before letting employees or owners drive fleet vehicles personally.
Can I add a vehicle to my fleet policy mid-term?
Yes. Most insurers let you add or remove vehicles during the policy term with a simple endorsement, and your premium is adjusted accordingly. It’s one of the practical advantages of fleet coverage over individual policies.
Get a Commercial Fleet Insurance Quote in Minutes
Let us take the hassle out of getting the commercial fleet vehicle insurance your company needs, and we’ll steer you in the right direction.
Fill out our online application for a free quote in minutes.
Our licensed brokers will shop our network of 50+ insurers to find the right coverage to suit your business and budget, answer questions, and issue your policy documents.
– Updated September 16, 2026.
Related Posts
Categories
Recent Posts
Franchise Insurance Requirements in Canada: What Your Franchise Agreement Requires
Your franchise agreement spells out the coverage you must carry before opening day. Here’s what each clause means, what it costs in Canada, and how to get your certificate in hand fast.
What Is Commercial General Liability (CGL) Insurance? A Guide for Canadian Small Businesses
A customer trips at your front door. A job goes sideways and floods a client's basement. Here's how commercial general liability (CGL) insurance protects your business from claims like these, what it costs, and how to get covered in minutes.
Workers’ Compensation vs Employers’ Liability Insurance: What’s the Difference?
Workers' comp and employers' liability insurance both deal with workplace injuries, but they're not interchangeable. Here's how each one works, who needs it, and why many Canadian small businesses carry both.